MicroStrategy sells 2.05M shares, repurchases $188M preferred stock, buys $82M BTC
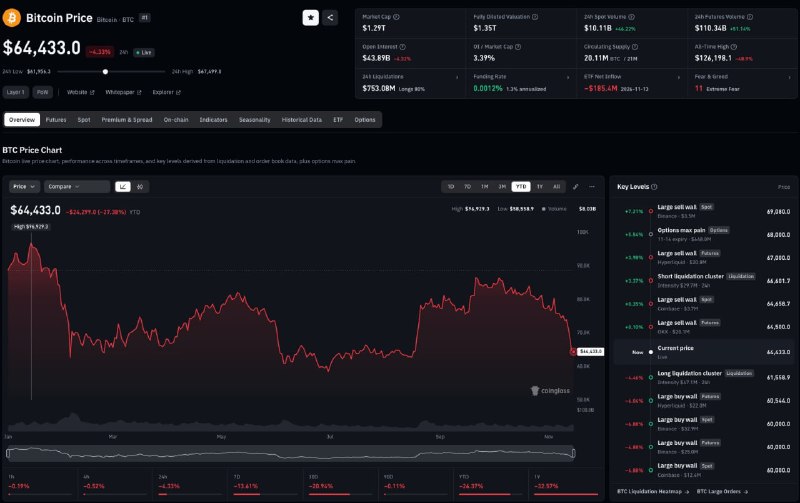
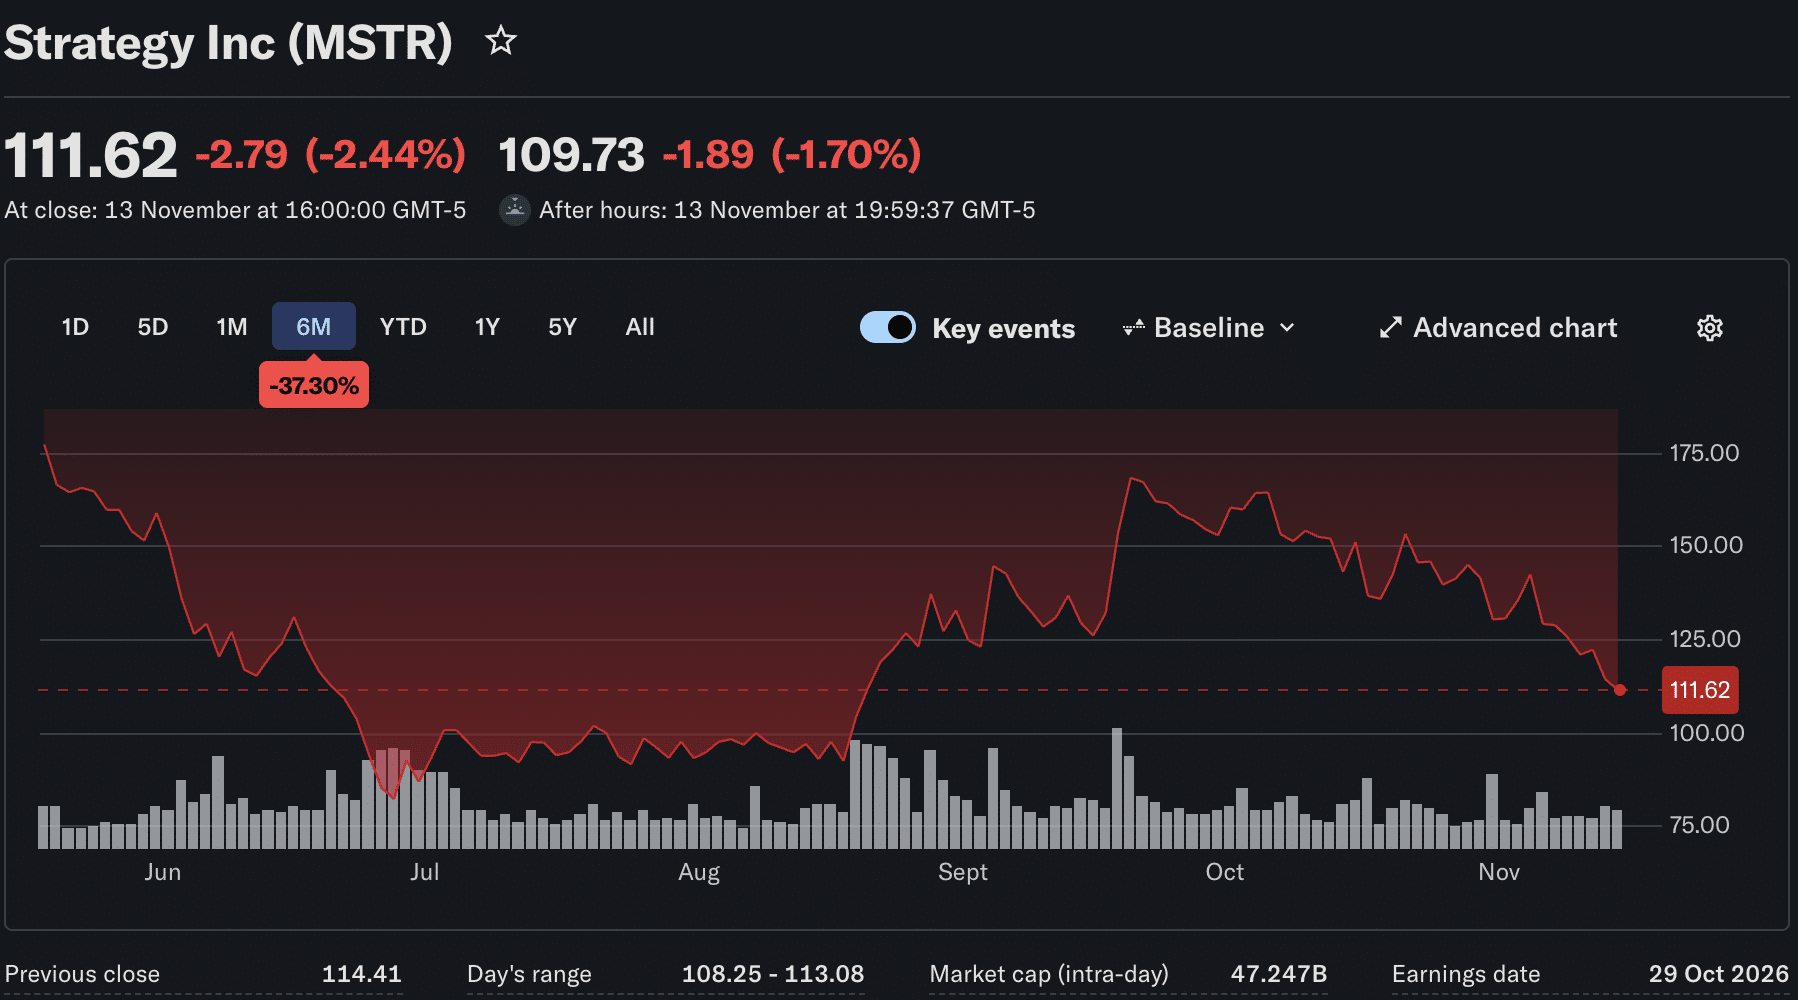
Michael Saylor’s Strategy, formerly MicroStrategy, ended the week lower: MSTR fell 13.4% over five days to about $111.60 and is down 37.3% over six months. Despite a large EPS beat in Q3 driven by mark-to-market Bitcoin gains, revenue missed consensus. A recent filing highlighted unusual capital allocation: new share issuance, partial BTC purchases, and a larger preferred stock repurchase, all against a backdrop of Bitcoin’s drop to just above $64,000 and MSTR trading below key moving averages.
Earnings, Capital Moves, and BTC Exposure
Q3 earnings on 29 October: EPS $44.75 versus $21.50 consensus; revenue $125.4 million below expectations. Profit primarily reflected mark-to-market gains on Bitcoin. The company sold about 2.05 million MSTR shares for net proceeds of $283.8 million. Allocation: $81.9 million to Bitcoin purchases and $188.3 million to repurchase preferred stock STRC. Current Bitcoin holdings: 850,364 BTC at an average acquisition cost of $75,456 per coin. With Bitcoin trading just above $64,000 after a 14% weekly decline, the position is below cost.
Technical Context for MSTR
MSTR trades below the 20-day ($139), 50-day ($149), and 200-day (~$133) moving averages. Daily RSI near 41 signals weak momentum, and MACD is negative. Key levels: support at $110, then $102; longer-term support near $87. Resistance: $126–$130 where moving averages converge, then ~$186. The trend remains bearish until a close back above $136–$140. A break below $110 increases downside risk.
Narrative and Forward Scenarios
The equity thesis remains a leveraged bet on Bitcoin’s recovery. Management highlights growing institutional demand and Bitcoin trading roughly 6% above its 200-week moving average. MSTR’s Bitcoin holdings have grown by about one-third while Bitcoin sits about 49% below its all-time high. A move toward six-figure Bitcoin would materially affect MSTR’s valuation due to the scale of its BTC relative to market cap.
Balance sheet signals: net leverage fell from 8.4% in Q2 to 2.4%; management indicates liabilities remain covered unless Bitcoin declines roughly 78%. A $4.77 billion reserve supports preferred dividends, reducing the likelihood of forced sales. Buying back preferred stock below par can increase Bitcoin per-share exposure. The company also has an unused $1 billion authorization for common stock buybacks. Sustained GAAP profitability could revive speculation about S&P 500 eligibility, but this remains uncertain.
Price Path Estimates and Risks
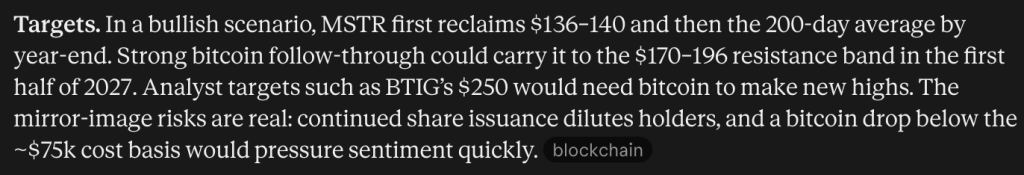
Perplexity AI’s bullish case: reclaim $136–$140 first, then potentially the 200-day moving average by year-end. With strong Bitcoin momentum, MSTR could test $170–$196 in the first half of 2027. Analyst targets such as BTIG’s $250 imply Bitcoin reaching new highs. Risks: continued share issuance dilutes equity holders, and Bitcoin trading below the roughly $75,000 cost basis pressures sentiment and equity value. Failure of $110 support exposes lower levels including $102 and potentially $87.
Market Intelligence: Crypto Analyst Reveals Upcoming Binance Listings
Market Intelligence: Crypto Analyst Predicts Best New Crypto to Hodl
The post appeared first on Coinspeaker.
Authors credited by the source: Daniel Francis
Published by Holder based on an external source.