FinCEN and Fed withdraw proposed crypto Travel Rule expansion for cross-border transfers
TL;DR: FinCEN and the Federal Reserve withdrew a proposed expansion of US recordkeeping and Travel Rule requirements that would have covered certain convertible virtual currency transfers and lowered the cross-border transfer threshold. Withdrawal removes the proposal and leaves existing anti-money-laundering obligations intact.
FinCEN issued two actions on November 6 that point in different directions. The agency severed MEXC Global’s access to the US financial system. It also withdrew a proposed update to the Recordkeeping and Travel Rule for funds transfers.
Per FinCEN’s notice, the withdrawn proposal would have amended requirements for convertible virtual currencies and certain digital assets, and lowered the threshold for transfers beginning or ending outside the United States. The Federal Reserve Board joined the withdrawal.
Withdrawal does not repeal the Travel Rule
A notice of proposed rulemaking outlines potential changes. Withdrawal stops those changes from advancing in that form. Existing reporting, customer-identification and information-sharing requirements remain.
The Travel Rule defines information financial institutions must collect or transmit for covered transfers. Digital asset implementation raises questions about service-provider identity, unhosted wallets and transfers spanning multiple systems. Amendments can shift where obligations attach or adjust thresholds. The broader compliance framework remains unless changed through separate law or rulemaking.
FinCEN characterizes this action as withdrawal of a proposal. Companies should update regulatory trackers and comment plans, and maintain controls required under current law.
Implications for crypto payments
Transfer-information rules affect customer experience and institutional operations. Expanded data collection increases operational cost, introduces friction in cross-border payments and influences bank–crypto business relationships. Proponents of stricter rules emphasize traceability for anti-money-laundering and sanctions enforcement. Opponents cite privacy, proportionality and implementation burden.
The withdrawal signals that agencies will not pursue this specific expansion now. Future rulemaking or targeted actions remain possible. Scope and thresholds in any later proposal are unknown.
This sits alongside FinCEN’s targeted action against MEXC: the agency can halt a broad proposal while deploying existing authorities against entities it identifies as riskful. The decisions are not mutually exclusive.
Operational focus for compliance teams
Banks, exchanges and payment providers should review the withdrawal materials, map any planned system changes that depended on the abandoned proposal, and keep transfer-screening and data-sharing controls in place unless legal counsel advises otherwise. Cross-border operators should track differences between US requirements and partner-jurisdiction rules.
For context on how regulation shifts access to payment rails and tokens without altering token technology, see coverage of stablecoin access changes in Europe: NewsBTC.
Next useful developments: a timetable for replacement rulemaking or updated agency guidance on affected transfers. Current state: a proposed reporting expansion has been withdrawn and the underlying AML regime continues.
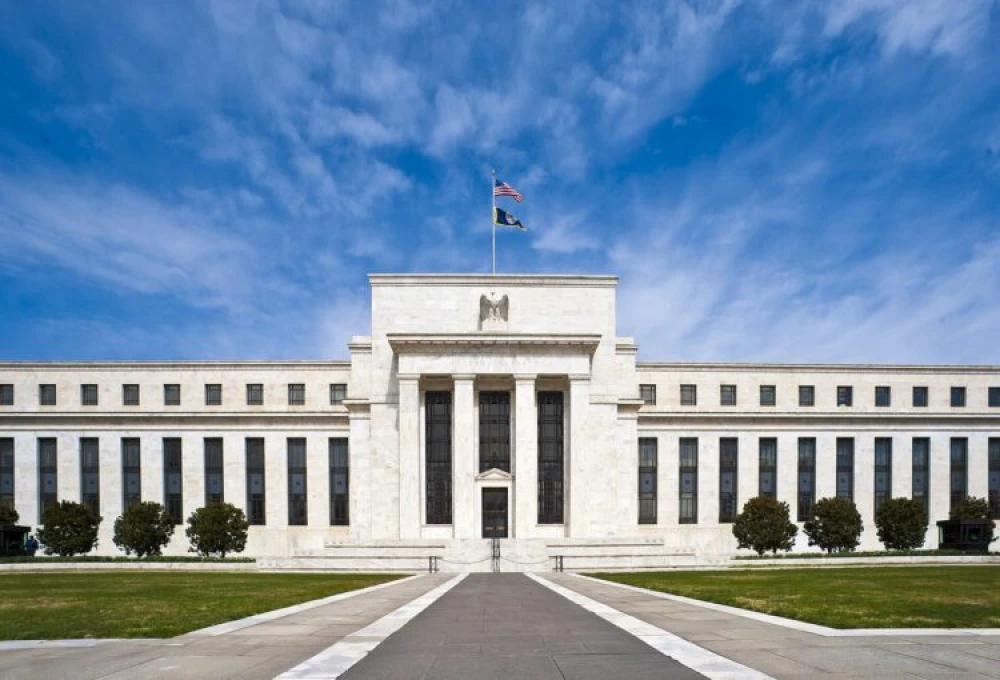
Featured image: Marriner S. Eccles Federal Reserve Board Building in Washington, D.C. Photo: Federal Reserve via Wikimedia Commons. License: Public Domain.
Authors credited by the source: NewsBTC Editorial Team
Published by Holder based on an external source.