VIX surges 70%, nears biggest daily gain since February 2018
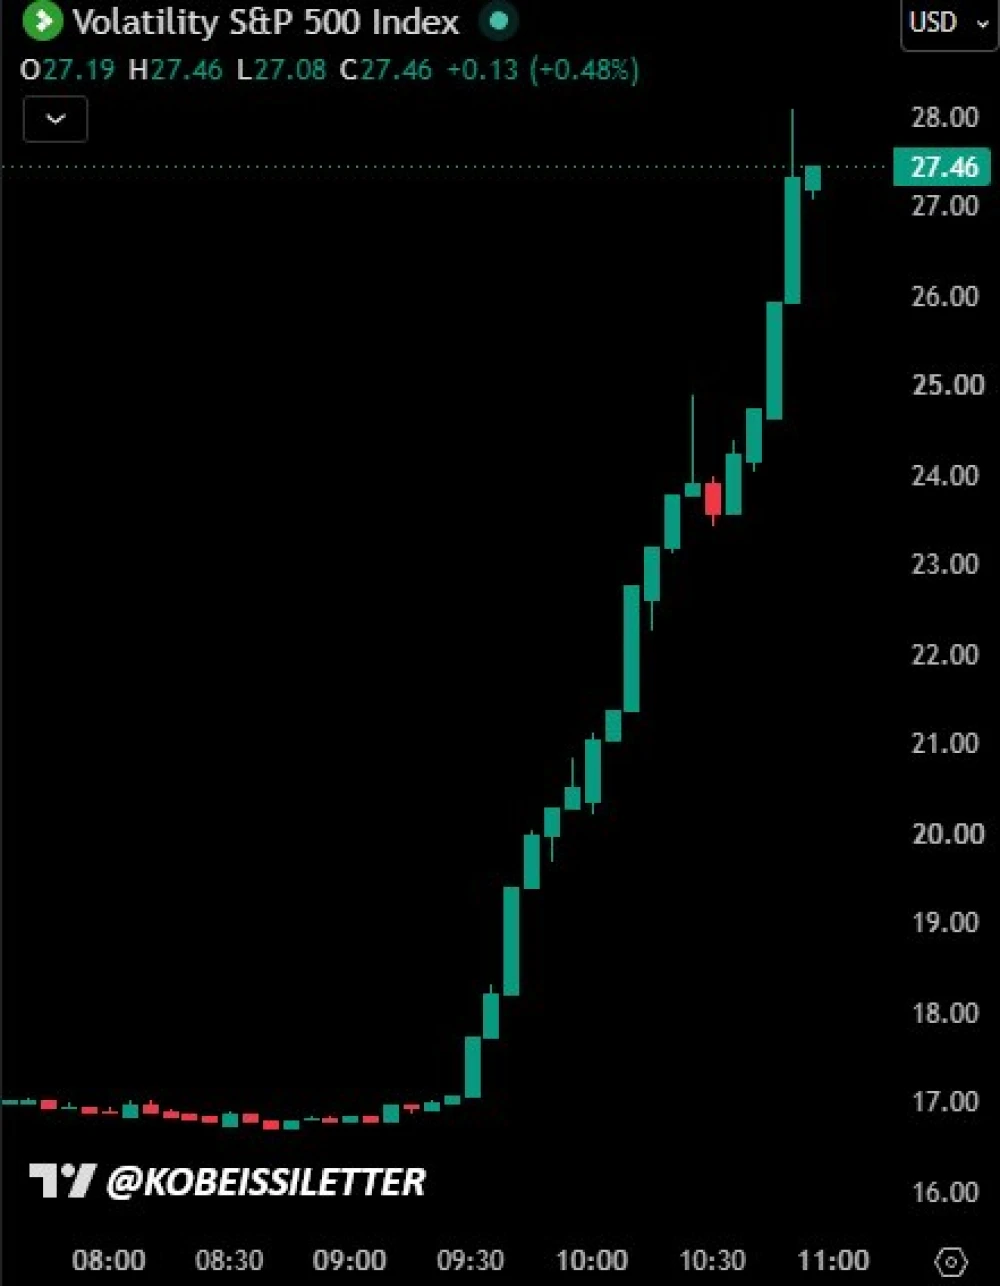
The Volatility Index (VIX) has jumped roughly 70 percent intraday. It is on track for the largest daily increase since February 2018 and exceeds any single-day jump recorded in March 2020. Source: The Kobeissi Letter.
Key facts:
- VIX measures 30-day implied volatility on S&P 500 options.
- A spike of this magnitude signals acute risk aversion and surging demand for downside hedges.
- Historical parallels: February 2018 volatility shock, March 2020 pandemic stress, other major risk-off episodes.
Implications for markets:
- Equities: elevated hedging costs, wider option premiums, higher probability of accelerated de-risking.
- Credit: risk premiums likely to widen, funding conditions can tighten.
- Liquidity: spreads and slippage tend to increase across risk assets during volatility shocks.
Crypto angle:
- Correlation: risk-off in equities often pressures Bitcoin and altcoins due to positive cross-asset beta.
- Derivatives: implied volatility and funding rates likely to reprice higher, with greater liquidation risk on leveraged positions.
- Market microstructure: wider spreads, thinner order books, more gap risk around key levels; basis and term structure can flip toward backwardation.
- Stablecoins: demand can rise as traders rotate to cash-like instruments, with transient stress possible on pegs during heavy flows.
What to monitor next:
- VIX closing level versus the intraday spike.
- S&P 500 breadth, high-yield credit spreads, and the Treasury MOVE index for confirmation of systemic stress.
- Bitcoin’s spot-derivatives signals: perp funding, open interest, options skew and term structure, and liquidation heatmaps.
- Exchange liquidity and stablecoin netflows across major venues.
Caveats:
- Percentage surges can be amplified when starting from a low VIX base.
- VIX reflects implied volatility, not realized moves. It indicates heightened hedging demand and uncertainty but not a guaranteed equity or crypto drawdown.
Authors credited by the source: thekobeissiletter
Published by Holder based on an external source.