World ID launches banking tools, separates human proof from payment approval
World introduced its banking-and-finance feature on October 18. For banks evaluating human verification, the key issue is scope: identify what each proof actually establishes and what the institution must still verify before approving payments or delegating authority.
TL;DR
- Human uniqueness, current presence and document attributes prove different facts and should not be treated as interchangeable.
- Identity evidence does not grant permission for every financial action.
- Recovery options, privacy controls and explicit transaction authorization remain required for complete control.
A human signal is not a complete payment approval
The launch statement targets financial institutions and AI-agent workflows. The value of any credential depends on mapping the specific fact it proves to the decision at hand.
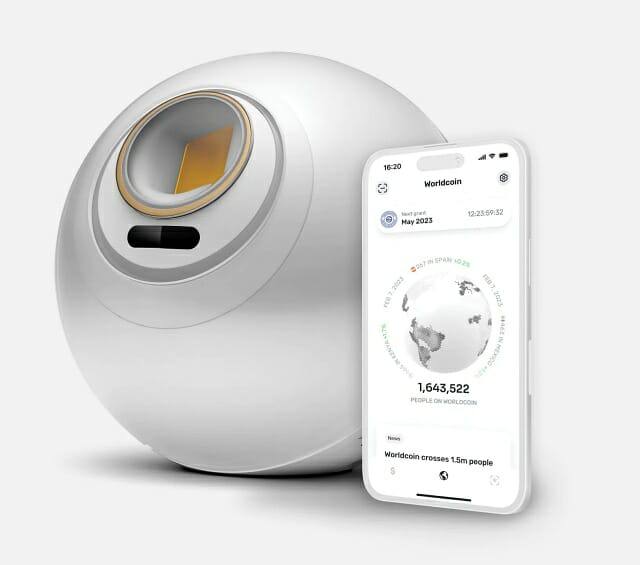
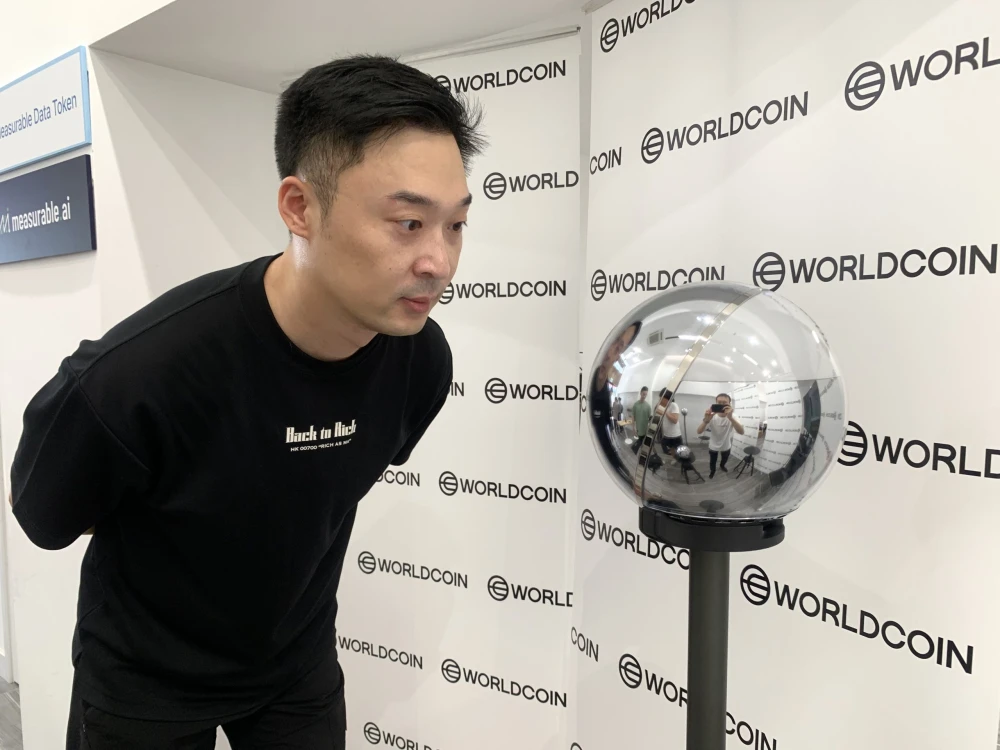
World’s technical overview defines three credentials. Proof of Human establishes uniqueness via Orb verification. Proof of Presence confirms current participation through a selfie-based check. Proof of Attributes confirms possession of a supported government document. Each answers a different question and should not be substituted for another.
Uniqueness does not equal authorization. An employee can be real yet unauthorized to approve a large transfer, and an authorized customer can be tricked about a recipient. Passing human verification does not resolve the commercial terms of a transaction.
NIST digital-identity guidance treats a standalone biometric as insufficient for strong authentication combinations. This is an external framework reference and does not assert that World meets any specific certification.
Transaction-risk screening remains a separate layer. Establishing facts about participants and assessing a payment’s destination are complementary and both required.
Agents increase the importance of clear delegation limits
For an assistant paying an invoice, proving a real customer stands behind the request is useful, but incomplete. The service must define which account the assistant can use, the spending limit, the permitted recipients and the expiry of authority.
Revocation must be available. A customer who loses a device or changes their mind needs a direct path to withdraw authority without relying on the agent. A record of earlier consent must not grant unlimited future transfers.
The operational challenge parallels controls in wallet financial-crime guidance. Understanding the relationship behind a transfer requires more than recognizing an address or accepting a single credential.
Privacy requires precise scoping. A proof can limit data in one verification step while the broader service still collects transaction records and account details. The complete data flow matters to the customer.
As AI-facing financial applications expand, robust implementations will state boundaries clearly: which fact is proven, which permission is granted and what additional checks govern movement of funds.
Written by the News Desk and edited by Samuel Rae.
Authors credited by the source: NewsBTC Editorial Team
Published by Holder based on an external source.