
Repeated identical trades raise wash trading concerns at Kashi
The weekend’s hot topic: Kashi’s wash trading controversy
In summary:
1. icobeast posted a chart suggesting that within crypto prediction markets on Polymarket vs. Kashi, Kashi has captured a dominant 96.7% share of volume.
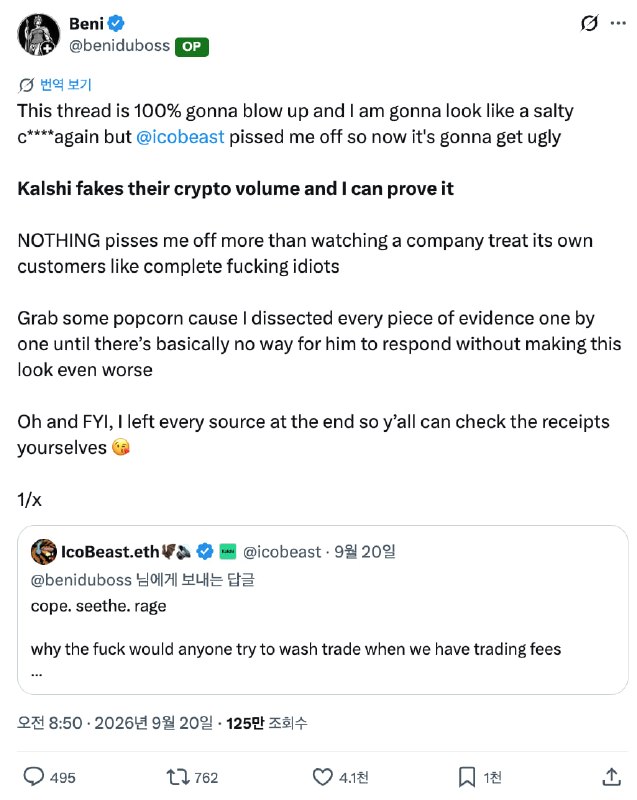
2. Someone named Beni commented that three-quarters of that volume looks like wash trading, and icobeast brushed it off, saying there are trading fees, so how could it be wash trading.
3. Beni then uploaded a long thread in response.
1) According to the incentive program extension application submitted to the CFTC in early September, eligible makers receive a 0.3 bp rebate paid by takers. It’s a zero-sum structure, so self-trading incurs no cost.
2) On an ETH basis, OI is 3.1M and daily volume is 538.6M, implying the entire open interest turns over 174 times per day. The top position on the leaderboard is only 17.6K.
3) There was a report in February that Kashi struck a deal with Jump Trading to provide liquidity in exchange for equity. From a market maker’s point of view, there’s plenty of incentive to pump the equity value.
4) In ETH execution data, the same-sized trades are repeatedly occurring, accounting for 55% of fills. This is data anyone can extract via the API.
5) Volume should be shown in number of contracts, but the UI displays it in dollars. If 100,000 contracts trade at $0.3, the volume shows as $100K (this seems to be the case at other prediction markets too).
4. icobeast posted a rebuttal:
1) The chart I cited is about market share in crypto prediction markets, not crypto perps.
2) Crypto perps are being run without rebates.
3) Market makers aren’t selected by Kashi; anyone can do it if they meet CFTC requirements.
4) Rebate/incentive programs are something all exchanges run.
icobeast did address some points, but the metrics Beni raised—like the repeated identical-volume trades and the excessive turnover—weren’t resolved. That’s actually heightened suspicion about possible wash trading.